Resume, job interview, AI shift
(Photo: Alex Green/Pexels)

AI Is Changing What Employers Look For In Job Candidates

The shift comes as employers face a surge in applications.


Artificial intelligence (AI) is changing how employers evaluate job candidates, with a growing number of companies shifting away from traditional resumes and toward skills-based hiring as AI makes it easier to customize applications, CNBC reports. 

Barb Hyman, founder and CEO of recruitment platform Sapia.ai, told the outlet that the traditional resume is “broken,” arguing that employers risk overlooking qualified candidates when they rely heavily on work histories and credentials.

“How many people are you missing out on because you’re relying on an artifact?” Hyman said.

The shift comes as employers face a surge in applications. U.K. graduate employers received an average of 140 applications per vacancy in 2025, the highest level recorded in three decades, according to Institute of Student Employers data.

At the same time, job seekers can use AI to quickly generate resumes and cover letters tailored to individual positions, making it more difficult for employers to distinguish candidates based on application materials alone.

Skills-based hiring is already gaining traction. About two-thirds of U.K. organizations have adopted the approach, according to 2026 research from recruitment firm Michael Page. Nearly 60% of candidates surveyed said they were more likely to apply for jobs defined by skills rather than traditional qualifications or career histories.

Employers are also reconsidering which abilities matter most as AI transforms the workplace.

James Broadhead, chief technology officer at AI decision-making company Taktile, told CNBC that technology has dramatically accelerated some engineering tasks. That shift has increased the importance of judgment, communication, self-reflection, and employees’ willingness to experiment with new AI tools.

Some companies are putting those abilities to the test during recruitment. Digital marketing and advertising agency PMG has graduate candidates complete practical exercises, collaborate in teams, and respond to client briefs.

“You don’t really know whether someone’s going to have the skills to do something until you challenge them to do it,” Josh Krichefski, PMG’s EMEA president, told the outlet. 

“The past doesn’t tell you that.”

Hyman also said AI could help employers identify candidates from a broader range of backgrounds by reducing reliance on hiring practices vulnerable to human bias.

Still, she said, people should retain the final say. AI can help screen candidates at scale, but hiring decisions should ultimately remain with the teams that will work with the new employee.

RELATED CONTENT: You Must Avoid These 8 Resume Killers At Any Cost

Sensori, equity, fundraising
AI-generated image

These 2 Black Women Raised $1M Without Venture Capital

Sensori Co-Founders Shanna Pearre and Darean Rhodes raised nearly $1 million from creators, athletes, and individual investors.


Shanna Pearre and Darean Rhodes, the founders behind Sensori, a nonalcoholic beverage company, have raised nearly $1 million without venture capital. Instead, they brought in more than 50 individual investors, including more than 40 creators, athletes, and other community investors.

The company launched after Pearre and Rhodes began building an audience around Sensori and its nonalcoholic products. Within three months, the startup had sold its first 5,000 cans. When Pearre shared on Instagram that Sensori was preparing to raise money, potential investors quickly reached out.

“The next day we woke up, and I had like 10 DMs and texts,” Pearre told Inc.

That interest eventually translated into checks. Rather than pursuing a conventional venture capital round, the founders chose to raise from people who could bring more than money to the business. The investor group includes creators who can introduce Sensori to new audiences while having an ownership stake in the company. Rhodes said this approach allowed them to keep full ownership of the company rather than taking institutional capital, which could have given investors significant influence over the company.

“They would definitely have the upper hand on me and Shanna,” Rhodes said. “We just could not give away that much control.”

That decision is particularly notable in a venture ecosystem where Black founders continue to receive a small share of U.S. venture funding. According to data cited by Inc., Black founders received approximately 0.48% of U.S. venture capital in 2024.

Sensori’s founders are taking a different route: generate revenue, build a loyal customer base, and allow people who believe in the company to participate in its growth. The approach is also reshaping the traditional relationship between brands and creators. Instead of simply paying creators to promote Sensori, the company has made some of them owners.

Creator Jenee Naylor, who invested after discovering Sensori on TikTok, said her faith in the product made the investment particularly compelling.

“I already believed in them,” Naylor said. She added, “I already enjoy this product. I will talk about it organically. You really can’t buy that.”

For Sensori, that community is becoming part of the company’s capital strategy. “It’s not equity handed out,” Rhodes said. “It’s ownership, and it gives creators an active role in building this business from day one.”

The founders expect Sensori to surpass $1 million in revenue this year and plan to consider institutional investment in 2027 — potentially from a position of greater leverage after proving the business on their own terms.

RELATED CONTENT: Brown Sugar Babe Founder Turns $300 Into $21M Fragrance Business

Tyler Perry, real estate, Puerto Rico
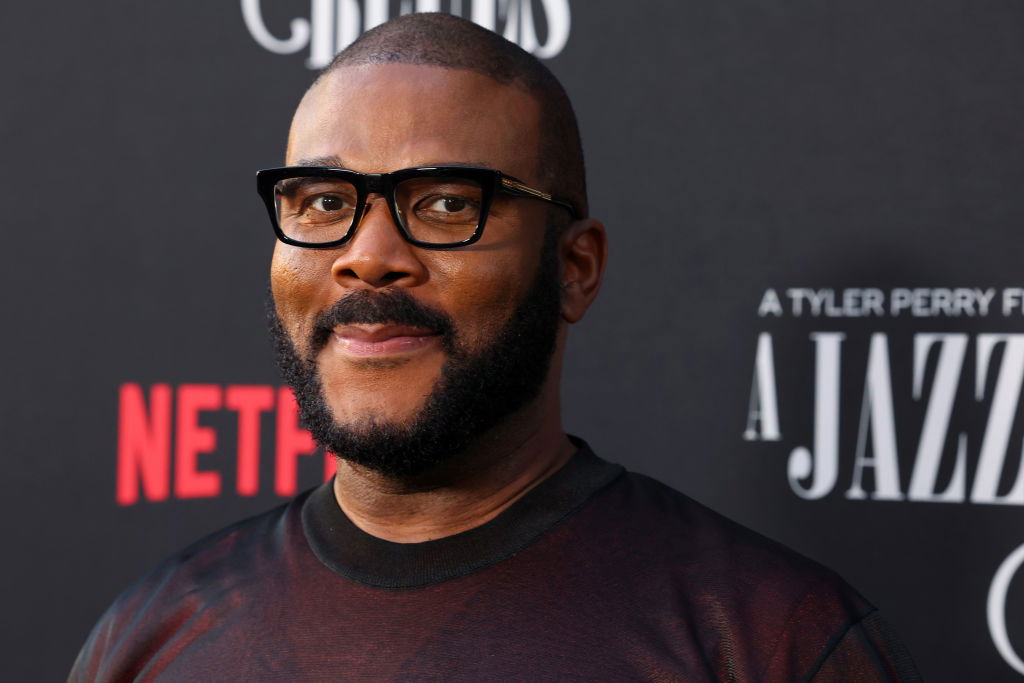
(Photo: Leon Bennett/Getty Images for Netflix)

Tyler Perry Puts $57M Beverly Hills Estate On The Market Amid Move To Puerto Rico

The media mogul lists his a 24,592-square-foot Beverly Hills estate just weeks after announcing that he plans to "slow down" and move to Puerto Rico.


Tyler Perry is putting a major piece of his real estate portfolio on the market as he prepares to trade Hollywood hustle for island living.

The iconic entertainment mogul has listed his sprawling Beverly Hills mansion for $57 million just weeks after revealing plans to move to Puerto Rico with his 11-year-old son, Aman. The property, which hit the market on Sept. 29, includes nine bedrooms, 15 bathrooms, a home theater, a gym, a music hall, a wine cellar, a game room, and multiple entertainment spaces, according to Realtor.com. The billionaire purchased the property for $4.3 million in 2004 and later transformed it into a 24,592-square-foot estate in 2012.

The “Why Did I Get Married?” filmmaker has hosted several A-list stars on the estate, including former President Barack Obama and Oprah Winfrey. Prince Harry and Meghan Markle also stayed at the estate in 2020 after stepping away from their royal duties, with Perry providing the couple a temporary home and security.

Perry’s next chapter appears to be less about celebrity and more about lifestyle. During an appearance on Today With Jenna & Sheinelle, the self-described workaholic announced that he plans to relocate to the U.S. Caribbean commonwealth to relax.

“Yep, moving to Puerto Rico at the top of the year, and I’m pulling back a whole lot,” Perry said.

The 57-year-old actor said that getting older changed how he views his demanding career.

“Getting older [inspired this]. It’s time to slow down a bit, enjoy more time with my son, and just take it all in.”

That shift could also represent a significant reshuffling of Perry’s real estate holdings. In addition to the Beverly Hills estate, he owns property in Wyoming, the Bahamas, and Georgia. Perry recently listed his Wyoming retreat for $39.5 million. He also owns a roughly 1,200-acre property near Atlanta, including a 35,000-square-foot residence. Nearby, Tyler Perry Studios occupies approximately 330 acres and includes production facilities designed to accommodate large-scale film and television projects.

RELATED CONTENT: Tyler Perry Pays Nearly $18K Lien For 81-Year-Old Homeowner

Jasmine McCall, Split Pay, campaign
Jasmine McCall, founder and CEO of Paybump and Chief of Financial Freedom at Split Pay (Photo courtesy of Jasmine McCall)

Jasmine McCall Joins Split Pay To Lead New Financial Freedom Campaign

The entrepreneur and financial educator will lead Split Pay's new campaign focused on financial flexibility and economic mobility.


Many of the 67% of Americans living paycheck to paycheck don’t have a problem with overspending. The issue occurs when their rent, car, and insurance bills are due at the same time. If they get paid twice a month, but all their bills are due on the first of the month, it can put them in a financial bind. That’s why Split Pay was created—to let workers turn big bills into two smaller ones, while their landlord or lender still gets paid in full and on time.

After helping over 150,000 people gain financial flexibility, the fintech startup announced a new Financial Freedom campaign on Thursday to equip millennials and Gen Z with tools to better manage monthly expenses. Paybump Founder and CEO Jasmine McCall will lead the campaign.

Launched in 2022, Split Pay is an AI-powered subscription platform that lets consumers split large recurring monthly expenses, like rent, mortgage payments, car payments, and student loans, into two payments. Subscribers make a portion of the bill on the original due date, while Split Pay covers the remaining balance. Users then repay that balance two weeks later. The company says the model is designed to give consumers more flexibility when major bills collide with their pay schedules.

For McCall, the new partnership connects directly to her work in financial education and economic mobility. She left a six-figure corporate position in 2022 to launch Paybump, a career and financial education subscription platform that has helped more than 20,000 workers land high-paying corporate jobs. The Atlanta-based entrepreneur has also built a sizable audience around personal finance and career advancement, with more than 656,000 YouTube subscribers and nearly 150,000 TikTok followers.

“I’ve always cared deeply about helping people create greater economic stability and feel more in control of their financial lives,” McCall said in a press release shared with BLACK ENTERPRISE. “This campaign allows us to meet millennials and Gen Z where they are and create more flexibility around some of their biggest financial obligations,” she said.

McCall added that she, too, once struggled with paying large monthly bills.

“As a young adult working at Pizza Hut, I remember the challenge of paying bills while living paycheck to paycheck. That’s why I’m excited about spearheading a campaign that equips people with a tool to get ahead of their finances,” she said.

As part of the campaign, McCall will help develop original content, community activations, and storytelling centered on financial flexibility. She will also oversee community initiatives intended to demonstrate Split Pay’s approach to helping consumers manage large monthly obligations.

“Jasmine has built a strong and loyal audience by making complex financial conversations feel practical and accessible,” said Andrew Borovsky, co-founder and CEO of Split Pay. “We’re excited to partner with her to launch the Financial Freedom campaign and deepen the way we engage with her audience and ours.”

The partnership comes as Split Pay scales following $125 million in Series A and Series B funding, with Khosla Ventures leading both rounds alongside Thrive Capital and Max Levchin, according to Axios. The company plans to use the capital to expand its consumer-facing marketing and experiential strategy.

For Split Pay, the collaboration places a recognizable financial educator and entrepreneur at the intersection of fintech, consumer marketing, and financial education as the company works to connect its product with younger consumers. McCall, who launched the media hub MacMedia Partners earlier this year, has also worked with brands including BMW, SoFi, BetterHelp, Printful, and Cloaked on consumer campaigns.

“I’ve climbed the corporate ladder, built and scaled a seven-figure business, and worked with the likes of BMW and SoFi,” she said. “However, this marks the first time that I can bring my collective experience and expertise to oversee a campaign that will transform lives.”

RELATED CONTENT: Your Credit Score Could Change How Much You Pay For A Home

decision wheel
Pixabay.com royalty-free image #8949580, 'ai generated, woman, office, work, laptop, business, modern, focused, career, corporate, environment, productivity, desk, workplace, computer, stylish, employee, glasses, smart, urban, executive, business woman, workspace, professional' uploaded by user TyliJura, retrieved from https://pixabay.com/illustrations/ai-generated-woman-office-work-8949580/ on September 5th, 2026. License details available at https://pixabay.com/en/service/terms/#usage - image is licensed under Creative Commons CC0 license

New Grads Struggle As Employers Raise The Bar For Entry-Level Jobs

The findings highlight a disconnect between employers’ expectations and the opportunities available to workers entering the labor market.


Recent college graduates say jobs advertised as entry-level increasingly require years of professional experience, creating another barrier for young workers trying to establish their careers, CNBC reports.

A Cengage Group survey found 77% of recent graduates believe employers are demanding too much experience for entry-level positions, while 75% said there are not enough jobs that genuinely qualify as entry-level. The findings highlight a disconnect between employers’ expectations and the opportunities available to workers entering the labor market.

The survey, conducted from April through August, included 1,100 recent U.S. graduates, 931 full-time hiring managers, and 759 college instructors.

Rachel Grandis, a 22-year-old Elon University graduate, told CNBC Make It that she has struggled to secure a full-time position despite graduating in May with a degree in strategic communications and gaining experience through internships and other jobs while in school.

“Entry-level to these companies is somebody who’s coming from three years of experience in the workforce,” Grandis told the outlet.

Employers are also confronting challenges as workplace demands evolve. Seventy-two percent of employers surveyed said the pace of workplace change has made it difficult for colleges and universities to keep their programs current. Employers identified teamwork, project coordination, and problem-solving as areas where some recent graduates need additional development.

Cengage CEO Michael Hansen said employers have raised expectations for new workers and increasingly want employees who can contribute quickly rather than require extensive training. Expanding internships, apprenticeships, and other opportunities for students to gain practical experience could help bridge the divide between education and employment.

Early-career opportunities also remain limited. Job postings on Handshake increased just 1% from July 2025 through June 2026 compared with the previous year, following three consecutive years of declines. Employers posted nearly twice as many full-time opportunities for the class of 2022 as they did for the class of 2026, according to the outlet.

The difficult transition into the workforce is also affecting how graduates view the value of higher education. Just 37% of those surveyed said their education was worth the cost, compared with 68% in 2022.

The findings underscore a persistent challenge for new graduates: gaining the professional experience employers increasingly expect while competing for fewer opportunities designed to help them acquire it.

RELATED CONTENT: Gen-Z Workers Navigate Tougher Job Market As AI Replaces Thousands Of Roles Monthly

paycheck to paycheck, financial strain
Vecteezy royalty-free image #26314292, 'Piggy bank with calculator on business graph on white background and copy space, financial goal concept. Business concept.', retrieved from Vecteezy on October 20th, 2024. License details available at https://www.vecteezy.com/licensing-agreement, image licensed under the Vecteezy Pro License

More Than 1 In 3 Americans Earning $300K Live Paycheck To Paycheck

High-income respondents who reported living paycheck to paycheck said they are struggling to save and make progress toward long-term financial goals.


More than one-third of Americans earning over $300,000 a year say they are living paycheck to paycheck, showing that financial pressure is reaching even some of the nation’s highest earners, Barron’s reports. 

The finding comes from research by Goldman Sachs examining the financial challenges workers face while preparing for retirement, according to the outlet. High-income respondents who reported living paycheck to paycheck said they were struggling to save and make progress toward long-term financial goals.

The financial strain extends across income levels. About 40% of working Americans surveyed by Goldman Sachs reported living paycheck to paycheck, while another 40% said they were making some financial progress but still struggled to balance current expenses with long-term goals. Nearly 60% of workers surveyed said they were concerned about outliving their retirement savings.

Those concerns come as households contend with the rising costs of major expenses. Goldman Sachs found that costs associated with housing, childcare, college, and healthcare have increased significantly since 2000, leaving workers to balance immediate financial obligations with retirement savings.

Workers with personalized financial plans also reported greater confidence in their retirement preparedness. Among respondents with a personalized plan, 83% said they believed they were on track for retirement, compared with 41% of those without one.

Employers are also placing greater emphasis on workers’ long-term financial security. A separate Goldman Sachs survey found that 72% of employers identified financial stability and retirement readiness as a top priority. Some employers are considering resources such as personalized financial guidance, managed accounts, and retirement income options to help workers navigate competing financial demands.

The findings illustrate a challenge facing workers across the income spectrum: A high salary does not necessarily eliminate financial pressure or guarantee that households can consistently build retirement savings while managing current expenses.

RELATED CONTENT: 1-Week Delay In Pay Can Cause Hardship For Folks Living Check-To-Check

OWN We Belong Here: The Story of Team Dream volleyball
AI-generated image

OWN’s New Documentary Spotlights Black Women Who Made Volleyball History

"We Belong Here: The Story of Team Dream" follows 12 Black women who came together to compete at the USA Volleyball Open National Championship.


OWN is spotlighting Black women athletes with a new documentary about the groundbreaking volleyball team Team Dream.

We Belong Here: The Story of Team Dream follows 12 Black women who came together in 2018 with limited practice time but a shared belief in one another as they prepared to compete in the USA Women’s Volleyball Championship. Led by NCAA champion Haley Eckerman, the players discovered they were making history as the first all-Black women’s professional volleyball team. Their story unfolds against a backdrop of limited representation in the sport, with the athletes using the volleyball court as a platform to challenge expectations and create a legacy.

The documentary is told entirely through the women’s own voices, without an external narrator. That approach puts their experiences — from the challenges they encountered to the joy, humor, friendship, pride, and determination that fueled the team — at the center of the story.

“Team Dream’s origin story is a powerful reminder of what happens when Black women step into their strength together,” Tina Perry, president of OWN, said in a press release.

Perry added that the women’s unity reflects “their power, their joy, and their unwavering belief in one another,” while describing their story as representative of the spirit of OWN Spotlight.

For audiences interested in the intersection of sports, representation, and Black women’s leadership, the documentary offers a look at how a group of athletes transformed a shared opportunity into a historic moment.

The film previously premiered at the Martha’s Vineyard African American Film Festival before its OWN debut. The documentary is also available through OWN’s digital and streaming platforms, including HBO Max, Discovery+, WatchOWN.tv, and connected TVs.

RELATED CONTENT: Savannah James Invests In ‘LOVB Los Angeles’ As Women’s Volleyball Expands

Earl

BLACK ENTERPRISE CEO, Earl ‘Butch’ Graves Jr., Extends An Invitation To The 10th Anniversary XCEL Summit For Men

The summit brings together high-achieving professionals across business, technology, finance, science, sports, and entertainment.


Earl “Butch” Graves Jr., CEO of BLACK ENTERPRISE, has officially convened corporate trailblazers, entrepreneurs, and visionary leaders nationwide for the landmark 10th anniversary of the XCEL Summit for Men, scheduled for Oct. 21–23, 2026, at the Hyatt Regency Grand Cypress in Orlando, Florida.

Designed to elevate executive influence and foster intergenerational wealth, the summit brings together high-achieving professionals across business, technology, finance, science, sports, and entertainment.

Who Are the Honorees?

Highlighting this year’s class, Graves noted, “This year we’re proud to honor an extraordinary group of men who represent excellence, achievement, leadership, and impact at the highest levels.”

How Does the XCEL Summit for Men Advance Executive Leadership?

Over three days of intensive workshops, keynote panels, and peer-to-peer mentorship, it delivers actionable strategies for navigating dynamic corporate environments. Programmed tracks address critical leadership issues, including navigating corporate restructuring, leveraging employer sponsorship for executive development, and maintaining mental health in modern executive roles.

“Ten years of excellence, ten years of brotherhood, ten years of XCEL,” Graves reflected. “Now it’s time to join us for what promises to be our most powerful gathering yet.”

To learn more about the 10th anniversary of XCEL Summit for Men, check out the event page on BE‘s website.

RELATED CONTENT: Here’s How You Can Secure Employer Sponsorship For The XCEL Summit For Men

co-living
AI-generated image

Co-Living Is On The Rise As Older Adults Search For Affordable Housing

As rents climb, co-living companies and lawmakers are turning unused bedrooms into affordable housing.


Amid America’s growing housing crisis, housing advocates are fighting to make better use of the empty bedrooms already available across the country.

Skyrocketing rents and the rising cost of living are pushing more adults to turn to co-living, an affordable housing option also known as house-sharing, room rentals, or “adult dorm rooms.” According to a report published by Zillow, the number of households sharing space with nonrelatives grew by more than 500,000 between 2017 and 2022. Meanwhile, nearly half of U.S. renter households were cost-burdened in 2024, spending more than 30% of their income on housing, according to Harvard University’s Joint Center for Housing Studies. Zillow also identified roughly 21 million “empty nest” households in 2022 — older households without children that have at least two extra bedrooms. That mismatch is creating an opening for companies that can turn underused residential space into rental units.

Launched in 2017, PadSplit lets property owners rent individual furnished bedrooms in single-family homes by the week. PadSplit gives renters access to a private bedroom and shared amenities, often with utilities included, while property owners can generate rental income from multiple rooms instead of leasing an entire property to one household. It mostly targets workers who earn too much to qualify for government subsidies but struggle to afford a conventional apartment. The company says it has housed more than 70,000 people in rooms that are substantially cheaper than a traditional apartment in the 30 markets where it operates.

The concept is essentially a modern version of single-room occupancy, or SRO housing, which was once common in American cities before zoning restrictions and redevelopment policies helped push the model out of the mainstream after World War II. Now legislators are reconsidering those restrictions.

In Rhode Island, lawmakers introduced the ROOM Act, legislation designed to remove barriers to co-living and SRO housing in zoning ordinances, building codes, and occupancy rules, reports Vox. The Institute for Justice, which developed the legislation, says it could apply to everything from a homeowner renting a spare bedroom to larger co-living properties created from converted commercial buildings.

Pennsylvania is also examining roommate restrictions. A 2026 analysis from the Pacific Legal Foundation found that nine of the state’s 10 largest cities limit how many unrelated adults can live together, potentially leaving existing bedrooms unavailable to renters.

In Shawnee, Kansas, property-management company HomeRoom challenged a city ordinance limiting unrelated adults from living together. A federal judge dismissed the constitutional challenge, citing a 1974 Supreme Court precedent.

The debate is about more than roommates. It is about whether America can expand its rental supply by monetizing space that already exists. As Sam Hooper of the Institute for Justice told Vox, “I think there’s this real problem of letting the perfect be the enemy of the good in housing policy.”

Co-living is on the rise as housing costs keep squeezing renters. And with millions of bedrooms potentially sitting underused, it could become even more popular.

RELATED CONTENT: Deion Sanders’ Son Says $14K Miami Rent Is ‘Insane’ As $11.89M Bankruptcy Fight Continues

savers credit, retirement
SDI Productions/Getty Images

IRS Saver’s Match Will Give Eligible Workers Up To $1K For Retirement

The benefit phases out as income increases.


Millions of low- and moderate-income Americans could receive up to $1,000 annually from the federal government to help build their retirement savings under a new program taking effect in 2027, CNBC reports. 

The Saver’s Match will replace the existing Saver’s Credit and provide eligible workers with a federal contribution based on money they save in qualifying retirement accounts. Established under the SECURE 2.0 Act of 2022, the program is designed to give lower-income workers a stronger incentive to save for retirement.

Eligible taxpayers can receive a match equal to 50% of the first $2,000 they contribute to a qualifying retirement account, providing a maximum federal contribution of $1,000 per person annually. Married couples filing jointly could each qualify for a match based on their individual contributions.

Income will determine how much taxpayers can receive. For 2027, single filers with modified adjusted gross income of $20,500 or less can qualify for the full 50% match. The threshold is $30,750 for heads of household and $41,000 for married couples filing jointly.

The benefit phases out as income increases. Single filers with income of $35,500 or more will not qualify, along with heads of household earning at least $53,250 and married couples filing jointly earning at least $71,000. Income thresholds will be adjusted for inflation after 2027.

The IRS has begun sending CP321J notices to taxpayers who claimed the Saver’s Credit on their 2025 tax returns or whose 2025 income placed them within the potential eligibility range for the new program. Receiving the notice does not guarantee eligibility, and taxpayers do not need to take action on it in 2026.

Workers can begin making qualifying contributions in 2027 to eligible accounts, including 401(k) savings and retirement accounts, 403(b), governmental 457(b) plans, and traditional and Roth IRAs. No minimum contribution is required to potentially qualify for a match.

Eligible taxpayers will claim the Saver’s Match by filing Form 8880-A with their 2027 federal income tax returns in 2028.

Unlike the Saver’s Credit, which generally reduces a taxpayer’s federal income tax liability, the Saver’s Match will be deposited into an eligible retirement account designated by the taxpayer. That structure allows the federal contribution to become part of the worker’s long-term retirement savings rather than providing an immediate tax break.

RELATED CONTENT: You’re Not Ready For Retirement If These Financial Elements Exist

×